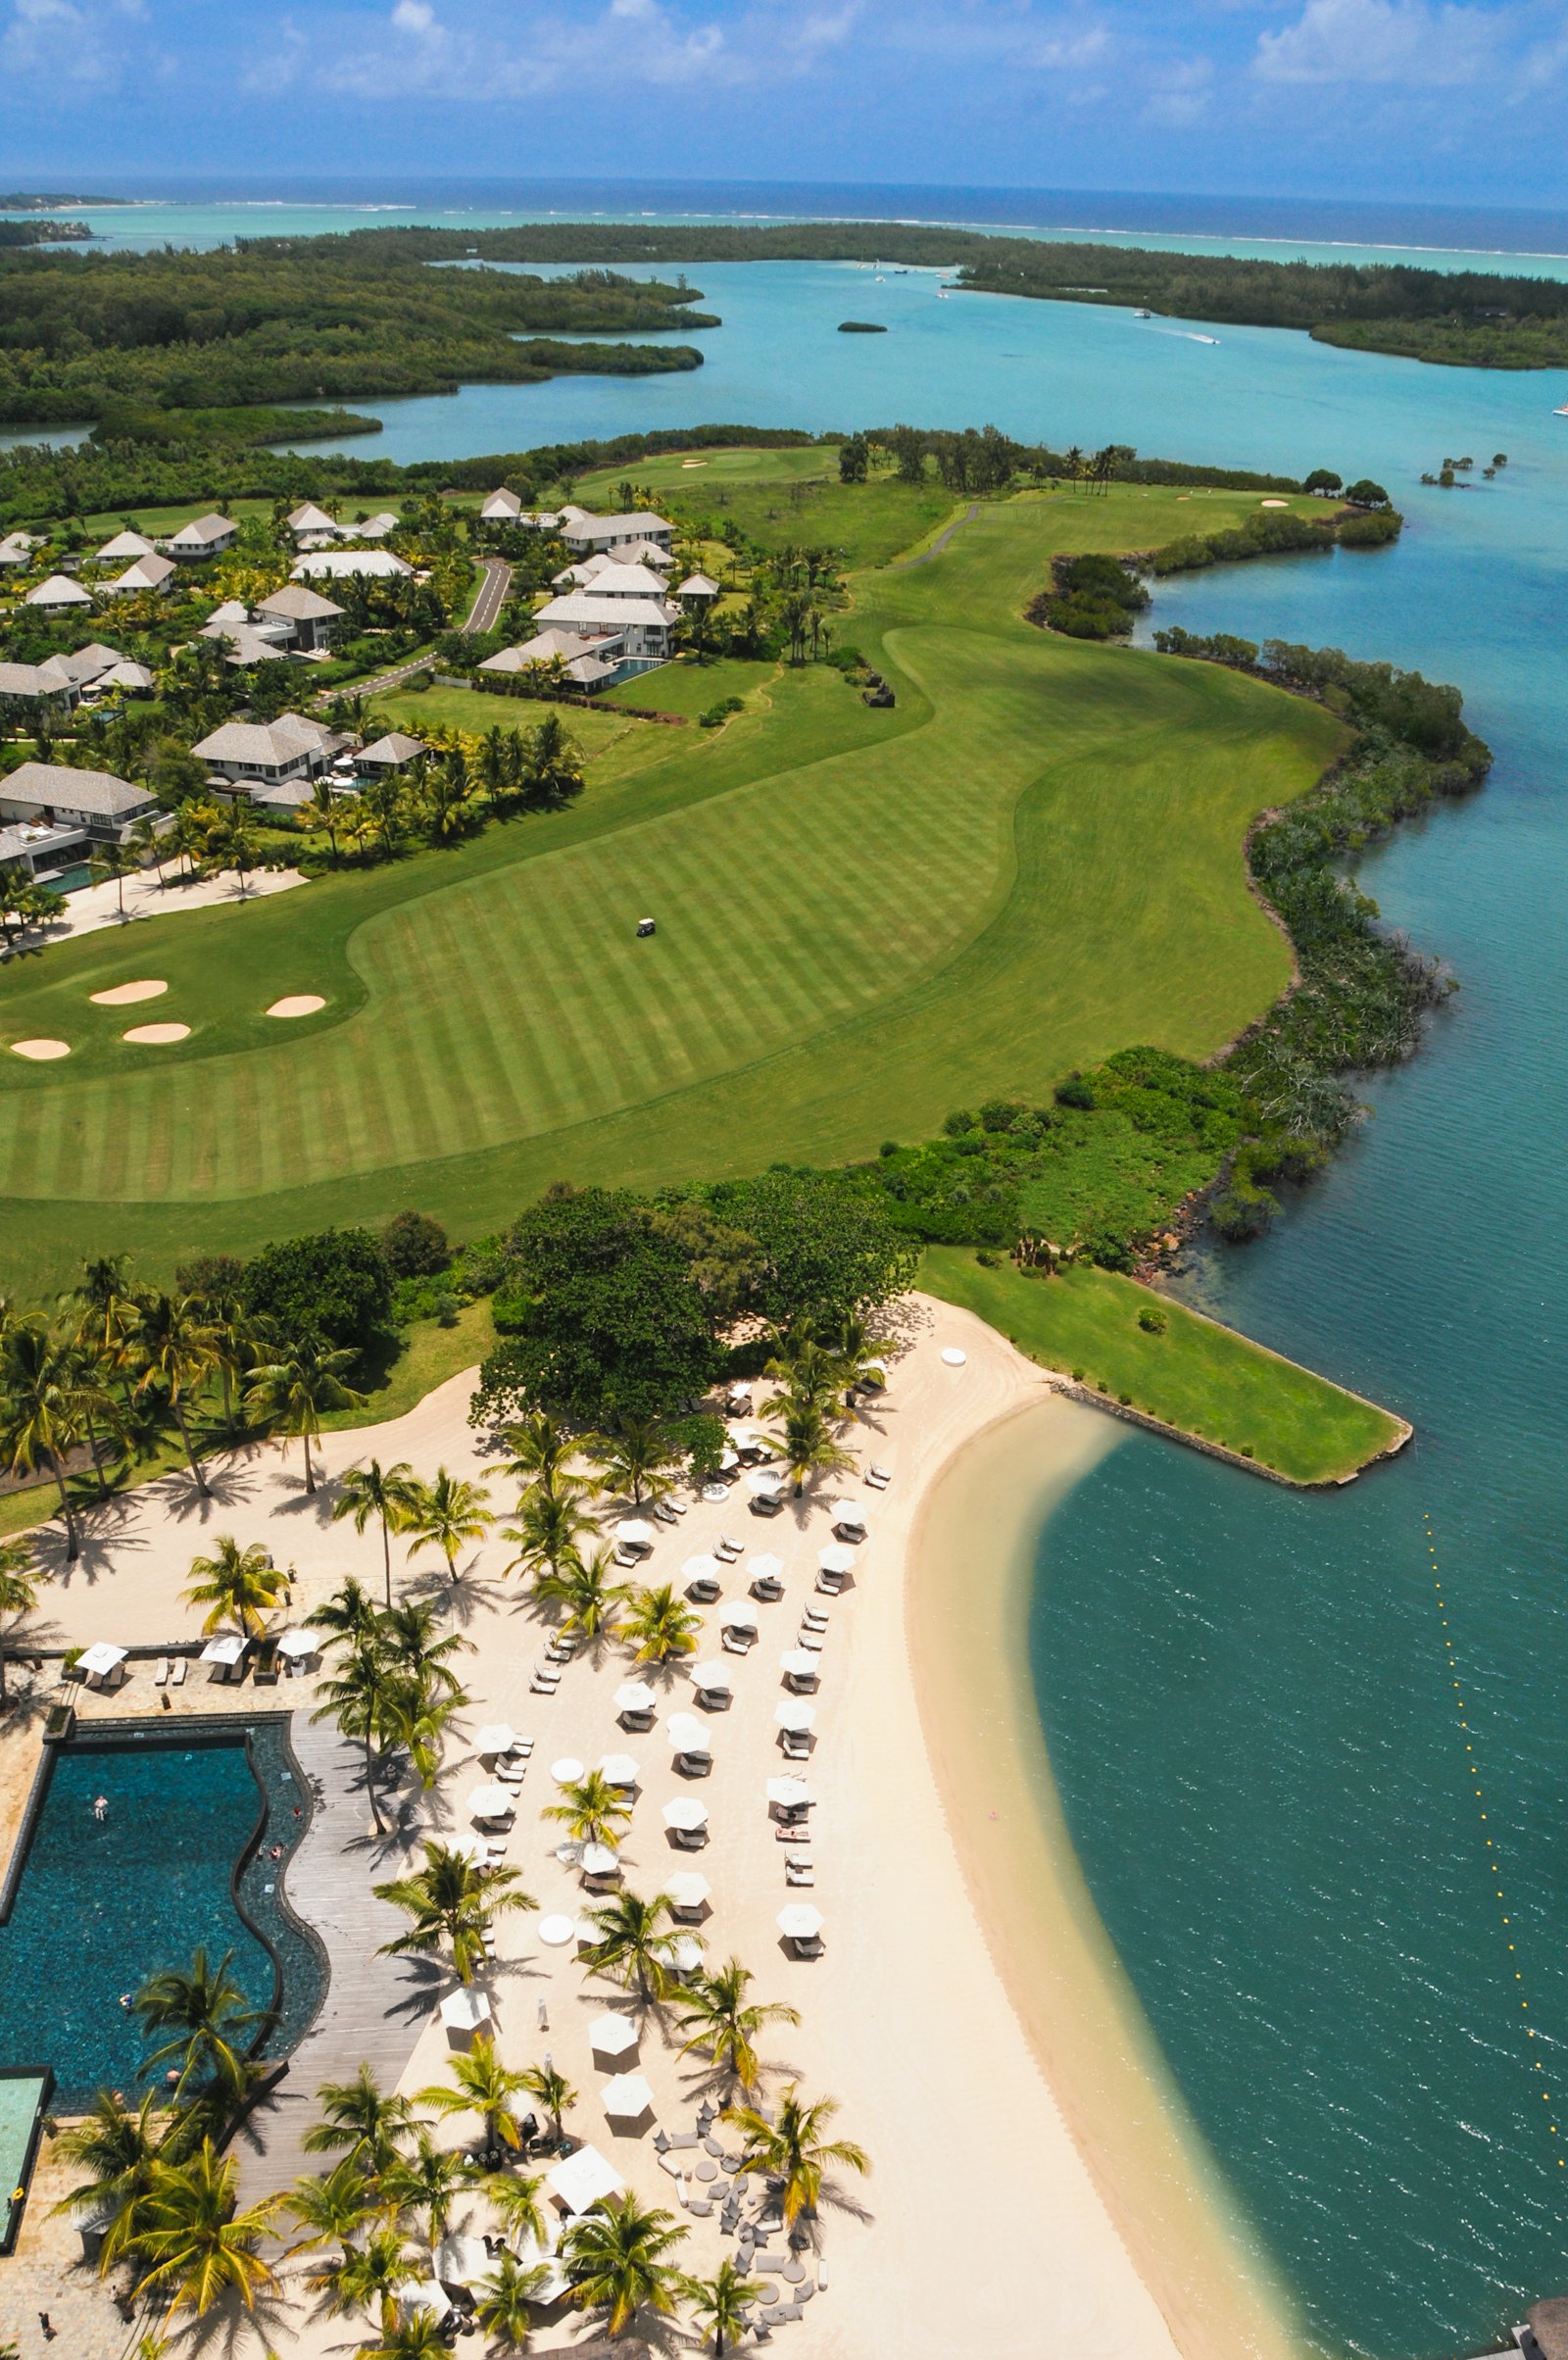
Yes. Mauritian banks do lend to non-residents. Typical parameters are a loan-to-value of up to around 70% (so a 30–40% deposit), interest rates in the region of 6–6.5%, and terms up to 25–30 years. You will generally need a local bank account, and depending on the bank the loan can be denominated in MUR, EUR or USD. Approval depends on your income, the bank's assessment and the specific project. Confirm current rates, currency options and conditions directly with the lender (MCB, SBM, ABSA and others) for your profile.
The core parameters: LTV, rate and term
Non-resident lending in Mauritius is well-established, particularly for purchases in approved schemes that banks know well. The headline figure is loan-to-value: non-residents can typically borrow up to around 70% of the property value, which means budgeting a deposit of roughly 30–40% of the price from your own funds. Interest rates for non-residents run broadly in the 6–6.5% range, and terms can extend to 25–30 years, subject to age and income conditions.
A local bank account is normally a prerequisite, both to service the loan and because the wider transaction (and the foreign-exchange rules covered in our repatriation question) runs through the banking system. Depending on the bank and your profile, the loan can be denominated in Mauritian rupees, euros or US dollars — a meaningful choice, because borrowing in the currency of your income can reduce exchange-rate risk. These are directional market parameters; the exact LTV, rate, term and currency offered will depend on the individual bank's assessment of you and the project.
Which banks, and what they assess
The main lenders active with international buyers include MCB, SBM and ABSA, among others, each with its own non-resident grid. Banks assess the usual factors — income and its stability, existing borrowing, the property and scheme, and the currency of the loan versus your income — and will ask for documentation accordingly. Pre-agreeing financing in principle before you commit to a purchase is prudent, especially given the 2026 duty change that affects the total cash required.
Because the duty rise to 10% from 1 July 2026 increases the non-financeable acquisition costs, model your cash requirement carefully: banks lend against value, but duty, notary fees and the deposit come from your own resources. The practical step is to get an indicative offer from one or two of the local banks early, confirm whether MUR, EUR or USD suits your income, and reconcile the financing with the full cost stack before signing. Rates and terms move, so treat any figure here as indicative and confirm with the bank directly.
Sources
Primary and expert sources behind this answer:
- Bank of Mauritius — Foreign-exchange framework, repatriation and non-resident lending ↗
- Economic Development Board (EDB) Mauritius — Acquisition of Immovable Property by Non-Citizens & Residence Permit guidelines ↗
This page is general information, not legal or tax advice. Mauritian property, residence, succession and tax rules are technical and change frequently — notably the 1 July 2026 registration-duty change. Every figure and rule here must be confirmed with a Mauritian notary (notaire), a tax adviser (fiscaliste) or a lawyer for your specific situation before you act.
Luxury buyer's agent, on the buyer's side only — Mauritius, Dubai, Marbella, Greece, the Maldives and the French Alps. Every price and every rule on this page is sourced (developers, sales offices, official EDB/MRA texts) and dated; pages are re-verified quarterly.
Our editorial method →Related questions
Explore our guides and listings
Buying property in Mauritius? Get an independent read first.
GADAIT is an independent luxury buyer's agent. We confirm the scheme, the tax, the residence reality and the real all-in cost for your specific case — before you commit.
Newsletter
Be among the privileged.
Subscribe to the Gadait International newsletter and receive the latest trends in the luxury market, along with exclusive opportunities for exceptional properties in advance.
Low frequency. High relevance.